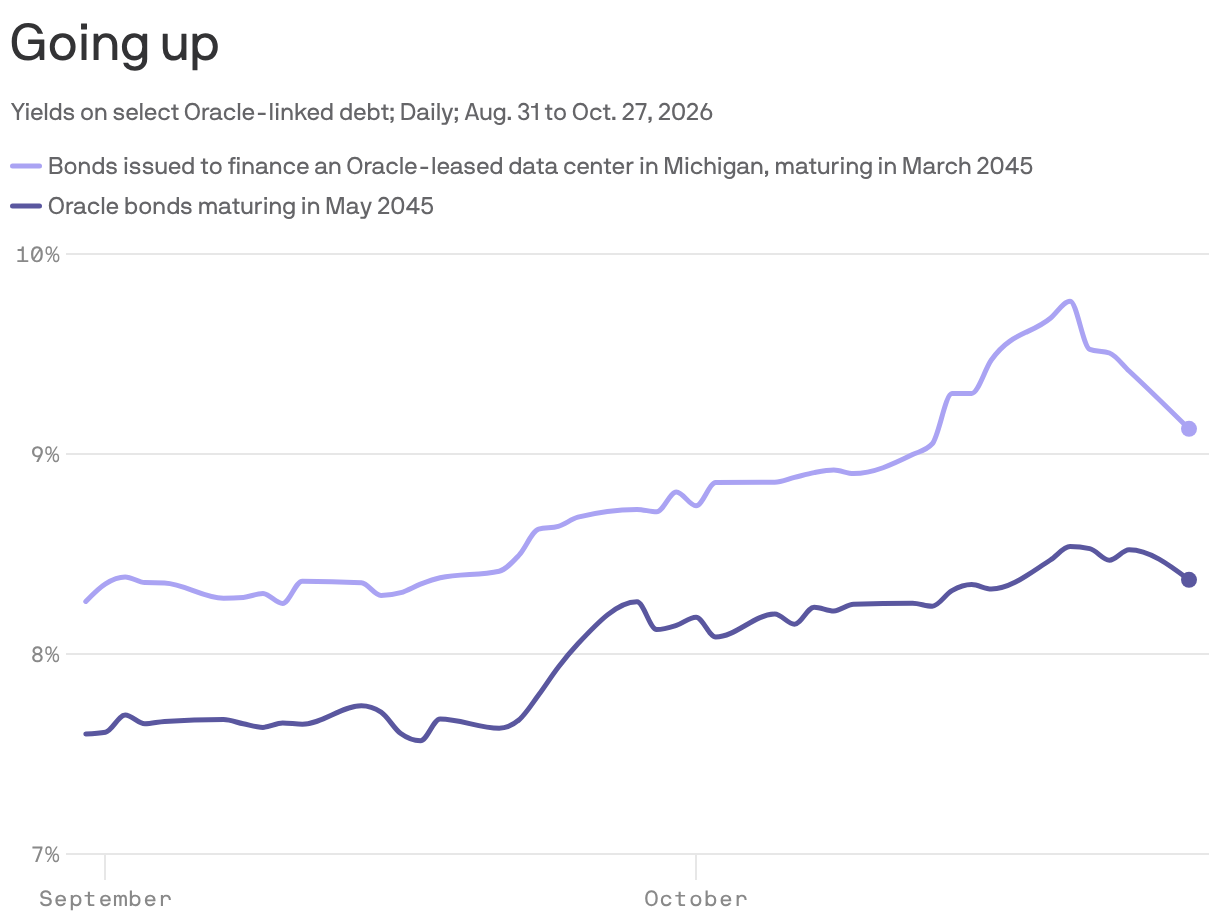
Even as AI borrowing roars on, the bond market is becoming more selective about which companies, projects and structures to finance. Why it matters: Bond markets determine borrowing costs. 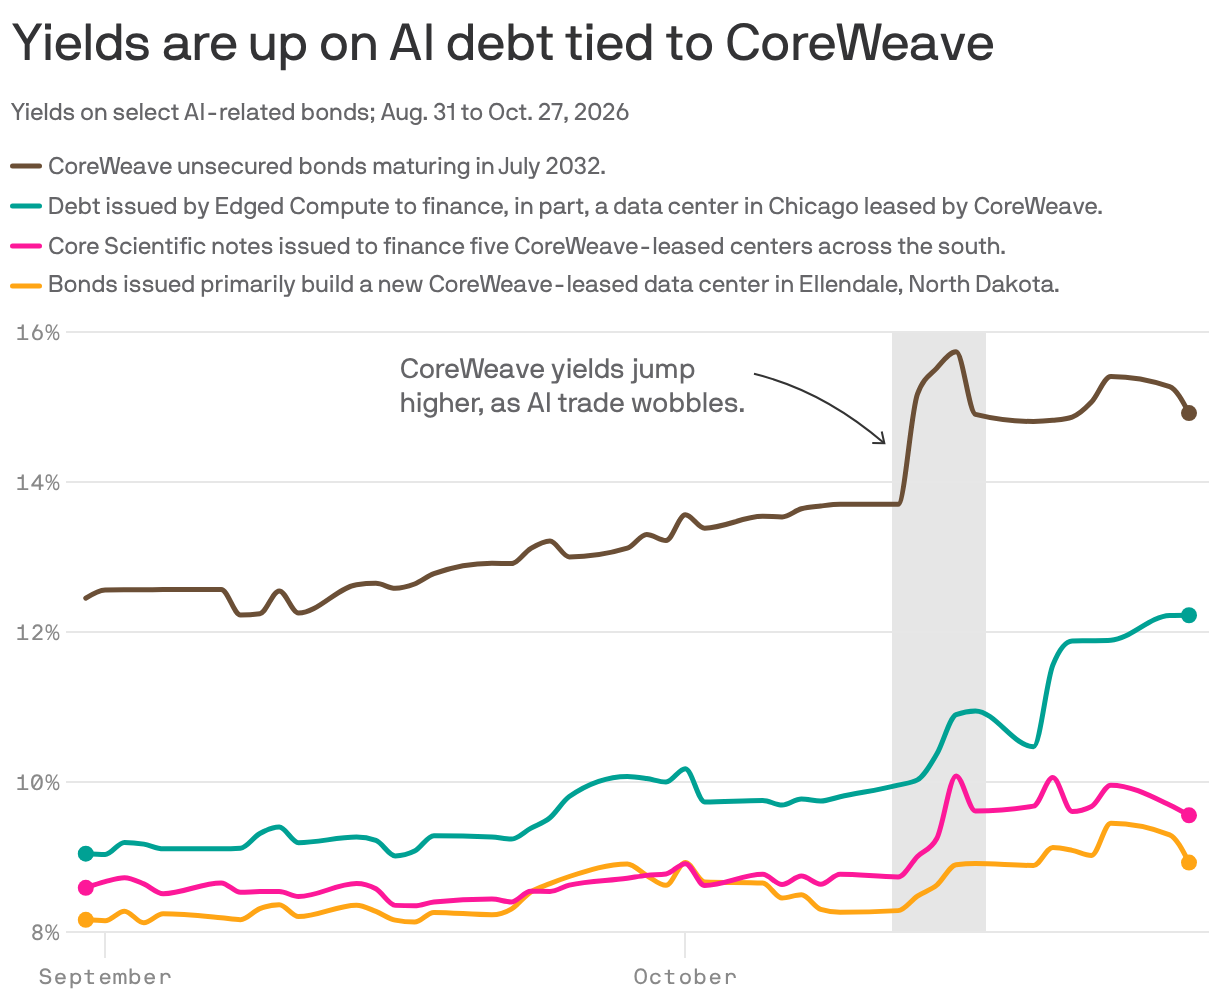
State of play: On the surface, things have calmed down in the corporate bond market since earlier this month, when yields on bonds issued by the heavily indebted AI player CoreWeave soared. (Bond yields move in the opposite direction of their prices, so this means CoreWeave's bond prices tumbled.) Yes, but: A CoreWeave-shaped dent remains in the bond market. Case in point: After CoreWeave bonds tumbled two weeks ago, pushing yields on its own unsecured bonds to highs of around 16%, bonds that are financing the development of data centers that CoreWeave has leased — including those issued by developer Edged Compute and ex-bitcoin miners Core Scientific and Applied Digital — also saw yields creeping higher. (See the chart, above.) What they're saying: "Tenant-specific risk was exposed during the October pullback, with CoreWeave and its associated neoclouds and data centers bearing the brunt of the selloff," wrote high-yield debt analysts at Citigroup last week, adding that data center bonds "are not immune to tenant default risk and can reprice quickly as that risk escalates." The bottom line: "We expect differentiation to persist as investors refine their views on the winners and losers of AI spending," the analysts said.