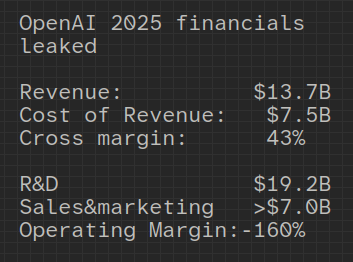
Source: Leaked financial docs show OpenAI is losing billions of dollars a year
This is not alarming for high growth company, per se. OpenAI revenues grew 3.5X from the last year. The question is what kind of business AI is at the end?
If foundational AI is like traditional highly competitive industry (airlines, telecom, or semiconductor manufacturing) with constantly high compute, electricity and R&D costs instead of traditional SaaS business, OpenAI’s trajectory is a structural trap.
Traditional SaaS businesses like Salesforce can have 80%+ gross margins because adding a new user costs practically zero.
Traditional hyperscalers can have 60+% gross margins because compute costs are relatively smaller and they have moats.
AI inference costs scale linearly with usage. The compute costs are relatively high. In commoditized businesses without moats, competition devolves into price wars. If AI business becomes like CapEx heavy utility, generating massive revenue with equally high investment and energy requirements combined with intense price competition, OpenAI is cooked.
When the smoke clears, companies that can spend with limited borrowing like Microsoft, Amazon, Alphabet, Facebook, Amazon are probably OK, but some may ease on with competition and settle into 2nd tier. Nvidia with all it’s backstop deals may end ‘owning’ most of the rest.